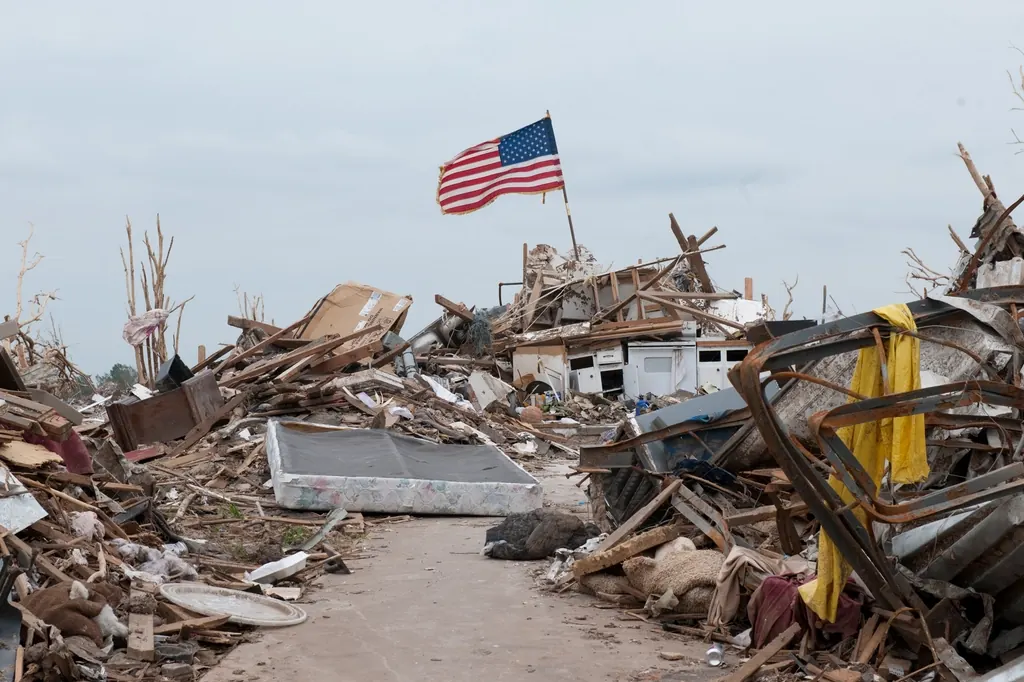
Indiana’s wind record
Indiana sits on the eastern edge of the central U.S. tornado corridor and sees tornadoes in most years, along with frequent straight-line wind events. The Palm Sunday outbreak of April 11, 1965, and the Super Outbreak of April 3, 1974, remain benchmarks. More recently the March 2, 2012, tornado through Henryville and Clark County, the 2013 and 2016 Kokomo tornadoes and the March 31, 2023, tornado that struck Sullivan show that damaging wind can arrive in any season. Derechos, such as the June 29, 2012, event that swept the state, and the remnants of Hurricane Ike in September 2008 caused widespread roof, siding and tree damage far from any tornado path.
What wind does that estimates miss
- Creased and unsealed shingles that look intact from the ground but have lost their seal strip.
- Racked framing: walls out of plumb, cracked trusses and nail pops that show up weeks later.
- Siding and soffit where replacement panels can’t be matched to the rest of the elevation.
- Outbuildings such as pole barns, detached garages and sheds that fall under other structures coverage.
- Debris impacts that dent doors, crack windows and puncture roofing far from the main damage path.
Total losses and near-total losses
When a tornado leaves a structure standing but damaged, the argument often becomes repair versus rebuild. We look at how much of the original structure can actually be saved, what code requires once walls are opened, and how demolition and debris removal are priced. On total losses, the question shifts to what it will genuinely cost to rebuild the same home in today’s market.
Wind and water together
Wind that opens a roof lets rain in. Interior water damage that follows a wind opening is usually treated very differently from flooding or seepage. We document the opening and the resulting interior damage together so the cause is clear.
Frequently asked questions
Is a derecho treated like a tornado?
For most property policies both are windstorm, so the same coverage and deductible apply. The documentation differs because derecho damage is broad and directional rather than a narrow path.
The carrier wants to repair my house but I think it’s a total loss. What now?
That is an amount-of-loss dispute appraisal can address. We compare a realistic repair scope, including code work and hidden structural damage, against the cost to rebuild.
Should I wait for the NWS survey before filing?
No. Report the claim promptly. National Weather Service surveys and storm reports are useful evidence later, and they’re publicly available.