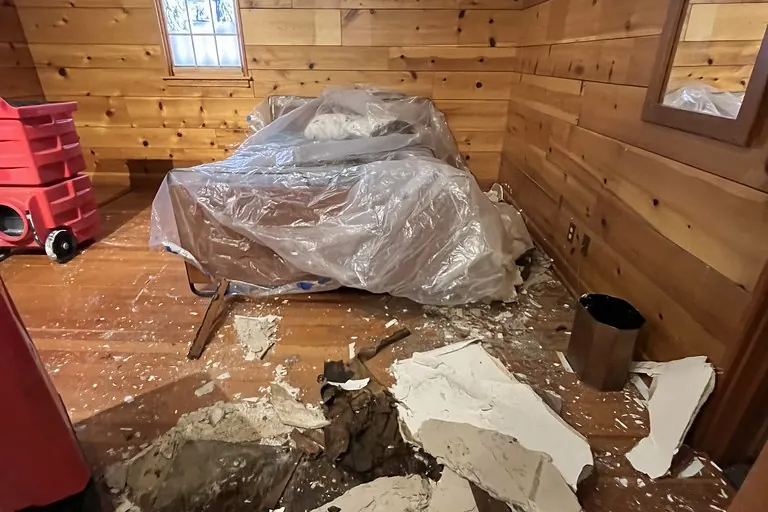
Indiana basements change water claims
Much of Indiana’s housing sits on full or partial basements, many finished as family rooms, offices and bedrooms. When a water heater fails or a supply line bursts upstairs, water follows gravity into drywall, carpet pad, framing and contents below. A basement that looked fine during a quick inspection may still be wet inside the walls days later.
Coverage first, then amount
Water claims hinge on the source. Sudden and accidental discharge from plumbing is commonly covered; long-term seepage, groundwater and surface flooding usually are not under a standard homeowners form. Sewer and drain backup and sump pump overflow are often covered only by an endorsement with its own limit. Appraisal is for the amount of a covered loss, so we start by confirming which parts of the damage the carrier has already accepted.
What a complete water valuation includes
- Mitigation: extraction, drying equipment days, antimicrobial treatment and monitoring logs.
- Tear-out and rebuild to the extent moisture readings justify, not just the visibly stained area.
- Flooring continuity: continuous hardwood, LVP and tile often can’t be patched without a visible break.
- Cabinetry and finishes that can’t be matched to undamaged sections.
- Contents stored in basements, which are frequently a large share of the loss.
- Mold remediation where it results from a covered loss and the policy’s mold sublimit allows it.
Freeze-related water losses
Many Indiana water claims start in January. When pipes freeze and split in exterior walls, crawlspaces or seasonal homes, the burst usually happens during the thaw. Policies often require reasonable steps to maintain heat in a vacant or unoccupied home, so timelines and thermostat records matter. Our freeze and snow-load page covers winter claims in more depth.
Frequently asked questions
Is a sump pump failure covered?
Usually only if your policy has a water backup or sump overflow endorsement, and those often carry a separate limit. Check your declarations page for the endorsement and its dollar cap.
The carrier only wants to replace two feet of drywall. Is that standard?
Flood cuts are a mitigation technique, not a repair standard. Whether more drywall, insulation or finish work is needed depends on moisture readings and how the wall can be repaired to a uniform finish.
Can appraisal resolve a mold claim?
If mold resulted from a covered water loss and the policy covers it, the cost of remediation can be part of the amount of loss, subject to any mold sublimit.